NYSE MAC Desk
Fed Recap:
STRAIGHT FROM THE TRADING FLOOR
by Michael P. Reinking, CFA & Eric Criscuolo
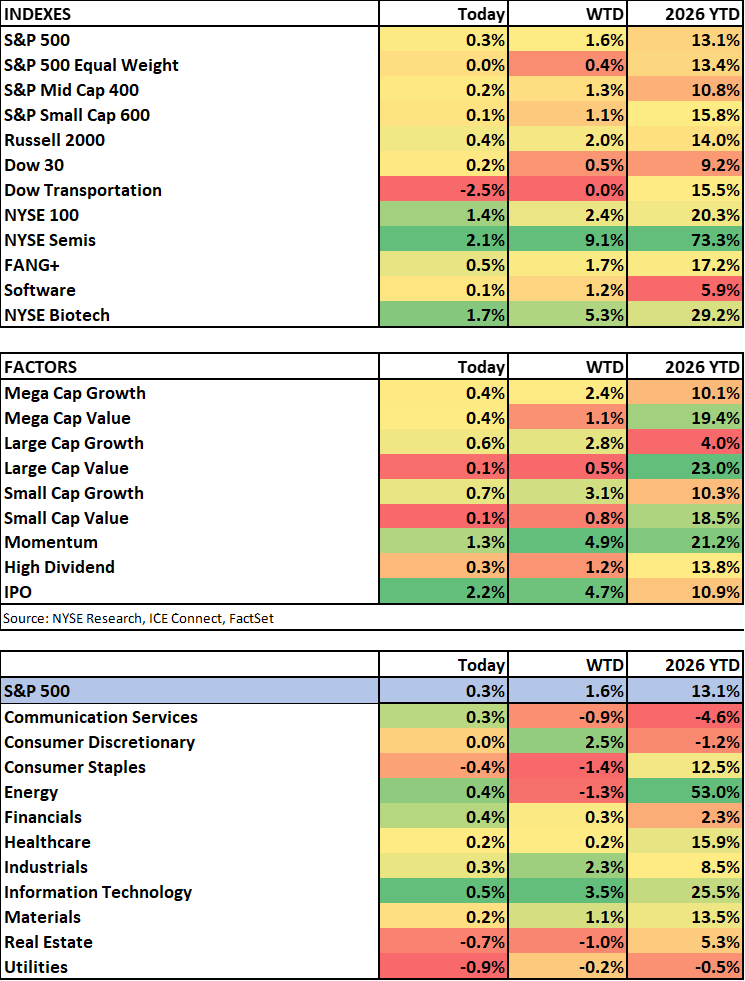
DOW 52,475 (+98), S&P 500 7,744 (+21), Russell 2000 2,831 (+12), NYSE FANG+ 18,528 (+99), ICE Brent Crude $114.21/barrel (+$0.33), Gold $4,084/oz (+$9), Bitcoin ~81.1k (+332)
- Hold as expected, with 2 dissenters
- Conditions tighter, but not tight
- Economic upgrade
- S&P ends around where it began
- ORCL news tries to upstage Warsh
MAC Desk Commentary:
As widely expected, the FOMC voted to maintain the Fed Funds rate at 3.75% to 4.00%. There were two dissenters this time around, Cook and Hammack, who wanted to raise the rate 25bp. This was Cook’s first dissent since joining the Fed in 2022, while Hammack has been a Hawkish dissenter before. Economic activity was upgraded from a “solid” pace to “strong”. The first look at Q3 GDP will be out tomorrow, by the way, along with PCE. The statement added, “The accumulation of more information will help the Committee determine the policy stance appropriate to ensure a timely return of inflation to the Committee’s 2 percent goal.”
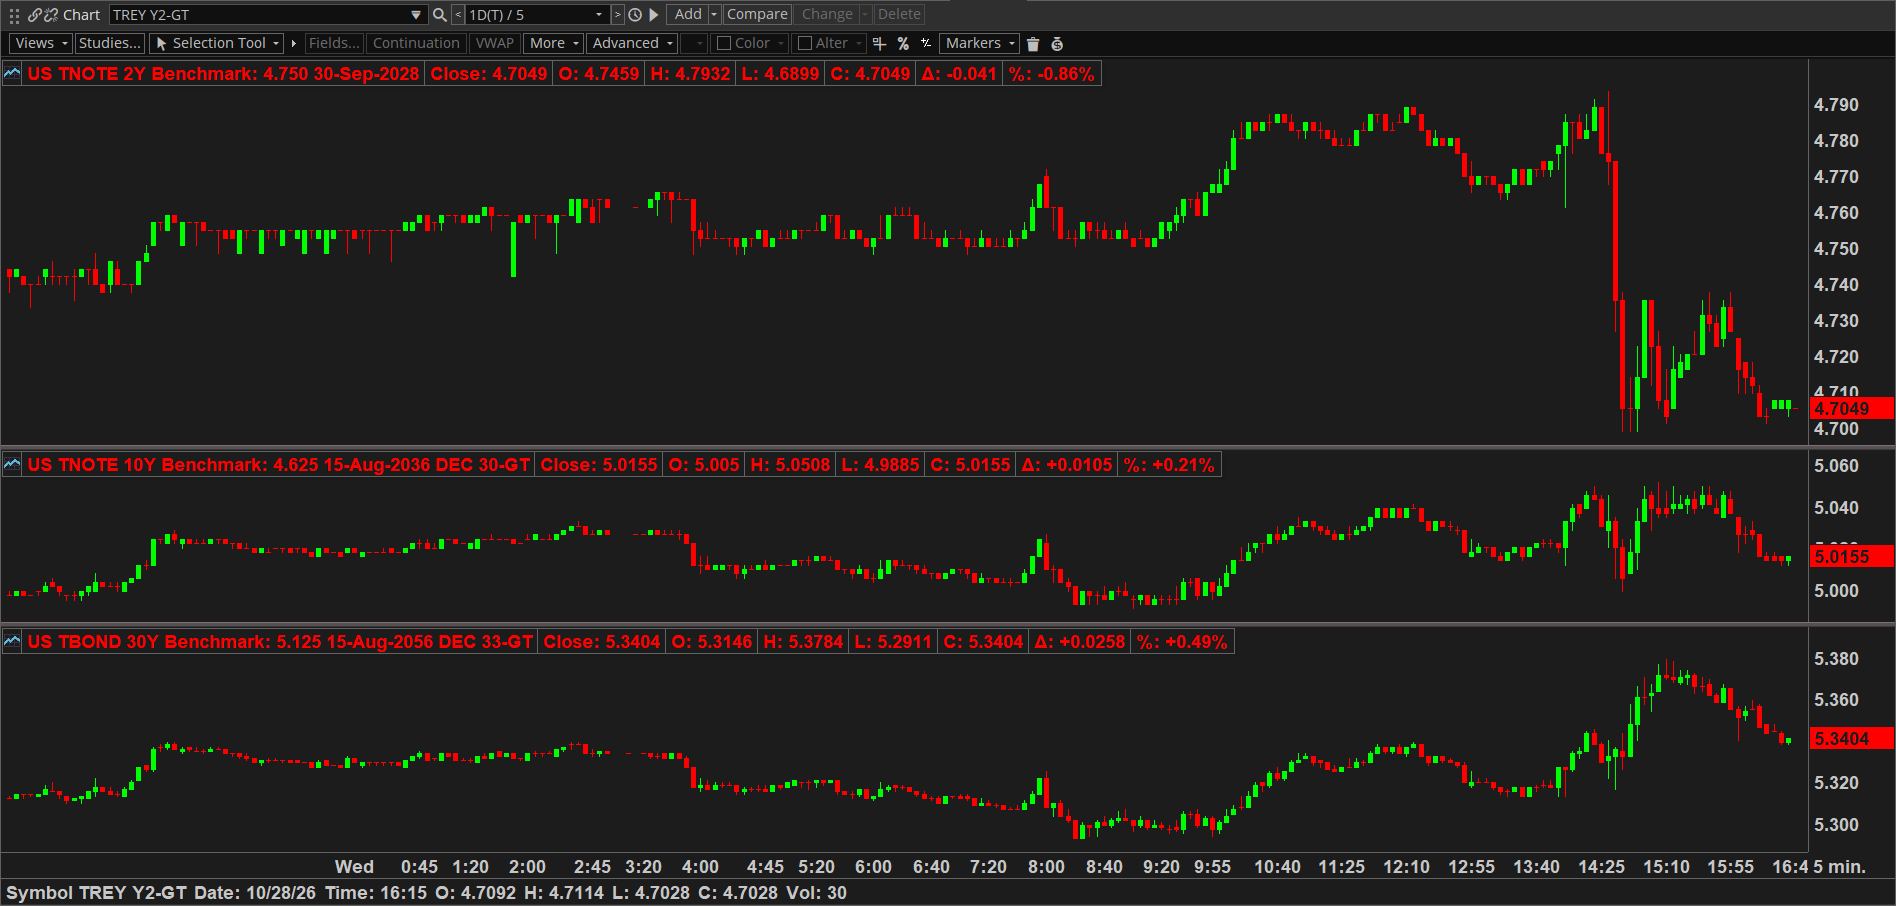
There was a little bit of something for everyone in today’s press conference but it ultimately left us in the same spot as when it started. Fed chair Warsh noted that much of this meeting’s discussion revolved around the Fed’s inflation mandate- not entirely surprising given the data and running commentary. A primary incremental takeaway was his acknowledgment that financial conditions started to become tighter and that the overwhelming consensus is that the “monetary medicine (from last meeting’s hike) is starting to work”. That seemed to have influenced the biggest reaction in the yield curve. 2ys dropped ~8bp around that comment, as it could indicate a reduced need for additional hikes. However, they later reversed some of that decline, and he caveated that statement by saying he was “unwilling and unable to call overall financial conditions tight”. While the 2y fell, the long-end sold off with 10/30y up 2-5bp from pre-press conference levels. During Warsh’s statement and the Q&A he noted that economic growth has strengthened, with Q3 poised to likely be even better. That probably helped push the long end higher before coming back in. There was also ORCL news around this time, which we will get to. The 2y ended down 5bp while 10 and 30y was flat to +2bp on the day.
The biggest development was an announcement of a change in the FOMC schedule. One meeting in 2027 will be focused on broad strategy, without a policy statement, and two in 2028. He hinted the 2027 strategy meeting would be in the fall, which make sense as it would give the Committee some time to analyze the findings of the task forces which are due at the end of the year. He also noted that on November 16th the Productivity and Jobs Task Force would hold a public field hearing to collect more data and provide insights into AI’s impact on the economy and productivity- something Warsh is very bullish on.
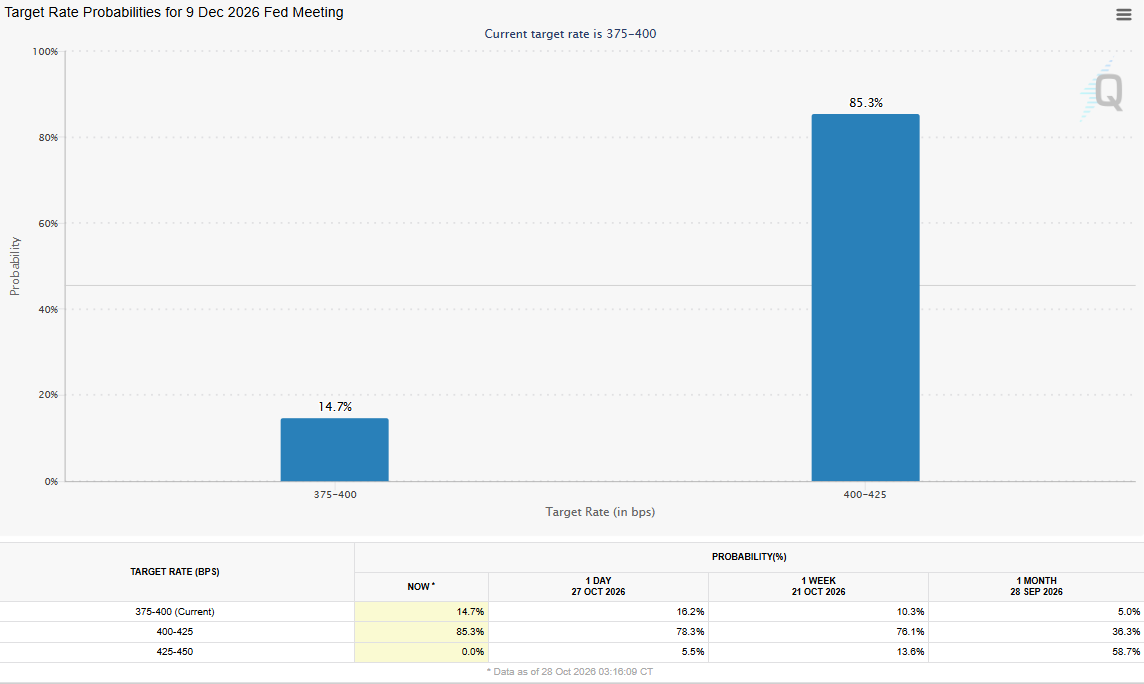
On the question of why not raise today if most members appear OK with that direction, Warsh essentially said the committee (outside of Hammack and Cook) wanted to wait for upcoming info between now and the December meeting. That would include important prints like GDP and 2 PCE/CPI readings. December expectations have adjusted, with a hike probability going from 78% to 85%.
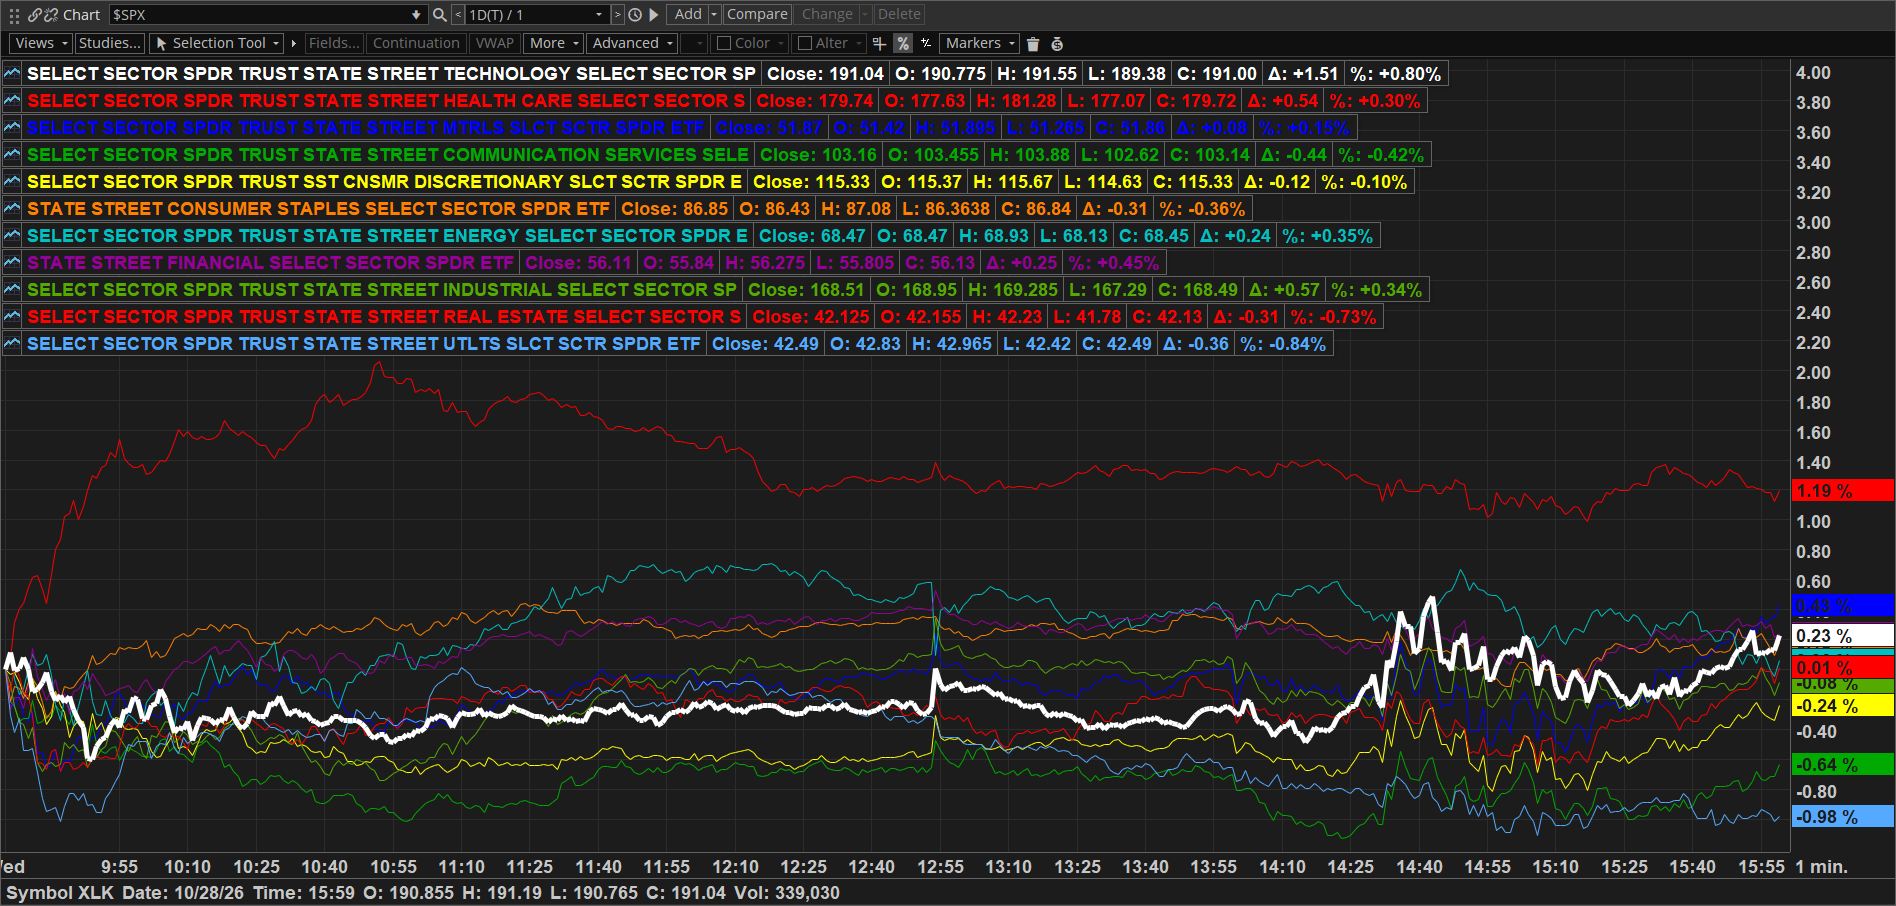
Despite some choppiness during the press conference, though muted by historical measures (~30pt range <0.5% in the S&P 500), equity markets ended pretty much where they were ahead of the rate decision (S&P +0.3%). However during the thirty-minute window following the decision and the press conference Oracle provided an update at its Investor Day which impacted markets and muddied the Fed analysis. The company re-affirmed its 2027 guidance and provided guidance out to 2030 that was largely in line with the street, calling for a 35% revenue CAGR, to ~$225B in 2030 and EPS of ~$21. The bigger news was a step-down in capex spending in 2029 which would support at least $30B of cash flow, well ahead of street estimates. The company also said it would only raise $20B of capital between now and 2030 ($10B equity and $10B debt). The stock rallied sharply after the news ending the day up ~10%. Oracle 5yr CDS which peaked around 350bps last week fell >20bps to 270bps. This broadly helped the tech trade into the end of the day though Nvidia which is the most exposed to their spending did end the session down 1%.
Microsoft (+3%) and Google (-8%) are moving in opposite directions after the close. The WSJ also reported that VP Vance sent a letter to the secretary of the National Security Council and previously the longest serving commander of the IRGC to reopen negotiations. ICE Brent is trading ~$114 down from the intraday high of $116.50.
Beyond GOOG and MSFT there's a lot more earnings tonight and tomorrow morning including F, FDX, NOW, Samsung, CAT, LLY, MA and MRK. US data tomorrow morning will include PCE and first look at Q3 GDP and jobless claims, plus the ECB rate decision. Enjoy your evening.
Connect with NYSE


By submitting this form you hereby expressly grant permission to use the information included thereunder to contact you for the purposes of sending periodic updates about ICE and/or its affiliates.
Your contact information will not be used for any purpose other than that for which your consent has been given. To learn more about our privacy policy, please click here.
© 2021 Intercontinental Exchange, Inc. All rights reserved. Intercontinental Exchange and ICE are trademarks of Intercontinental Exchange, Inc. or its affiliates. For more information regarding registered trademarks see: intercontinentalexchange.com/terms-of-usea