STRAIGHT FROM THE TRADING FLOOR
by Eric Criscuolo - Market Strategist
Published on 10/26/26 (a/o 1:30 pm)
DOW 52,287 (+72), S&P 500 7,674 (+50), Russell 2000 2,795 (+19), NYSE FANG+ 18,324 (+111), ICE Brent Crude $116.07/barrel (-$0.65), Gold $4,035/oz (+$27), Bitcoin ~80.0k (-1257)
- Lots of AI capital raising
- Equities higher on the Sports Equinox
- Tech leading; 7/11 sectors higher
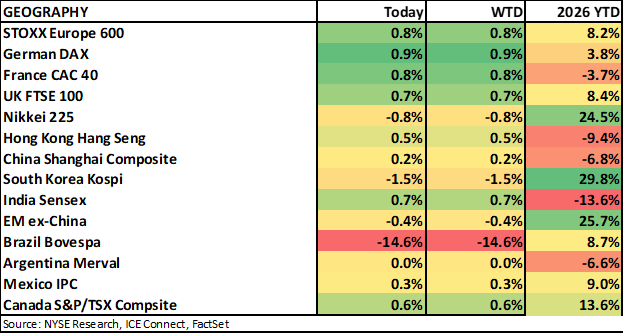
- Brazil getting waxed
- Check out some of the recent ICE Data/Content:
- Inside the ICE House
- Episode 564: Diary of A CEO's Steven Bartlett on Embarrassment, Obsession, and the Human Edge
- ETF Central: Introducing the Schwab International Bond ETF
- NYSE Research: The Busiest room on Wall Street
- ICE Mortgage Monitor: ARM Demand Hits Nearly Four-Year High on Rising Mortgage Rates
- Market Storylines
MAC Desk Commentary:
Equity markets were mixed last week with tech underperforming for the third consecutive week. The S&P 500 fell 0.5% as the AI trade continued to unwind amidst growing concerns about capital constraints. Oil prices were up ~5% trading to fresh highs. However, Treasury yields pulled back. This helped the equal-weight and small/midcap indices outperform.
There were two significant surprises over the weekend. The New York Football Giants going to Houston and beating the Texans, and Luiz Inácio Lula da Silva (Lula) winning Brazil’s presidential election after losing the first round to Jair Bolsonaro - the first time that happened in modern history. Bolsonaro’s preliminary win on Oct 4 led to a strong ~10% rally in the Brazilian stocks. There's controversy around the latest results after a court-ordered extension of voting, and Bolsonaro is looking to have the results annulled. Brazil stocks got smoked this morning.
Beyond the Giants and Brazil, the news was filled with AI financing discussions over the weekend. Elon Musk threw rocket fuel on the neocloud fire when he raised questions about the viability of the the businesses, posting, “That means the 200+ neoclouds are going to see guppy-level death and consolidation. Some will make it through, but not many.” SpaceX then announced a $40 billion finance lease for Nvidia GPUs with Apollo.
Meta followed up with plans to raise up to $95B in capital. The company filed the first piece: $22.5B in Class A shares and $12.5B in preferred stock, with NVDA, AMD and AVGO reportedly expressing interest in purchasing $5B of the raise. The second piece would be up to a $60B ATM of the company’s Class C shares when they begin trading in early 2027. An equity offering of some kind was expected heading into last week’s earnings, and especially when the company announced the new Class C shares. This also follows an interview on Friday, when Amazon’s CEO Andy Jassy said much of its 2027 cloud capacity has been booked and a good chunk of 2028. All of this led into the long awaited official Anthropic S-1, which finally published, after weeks of partial leaks. The WSJ reported the IPO is targeted for the week of November 16.
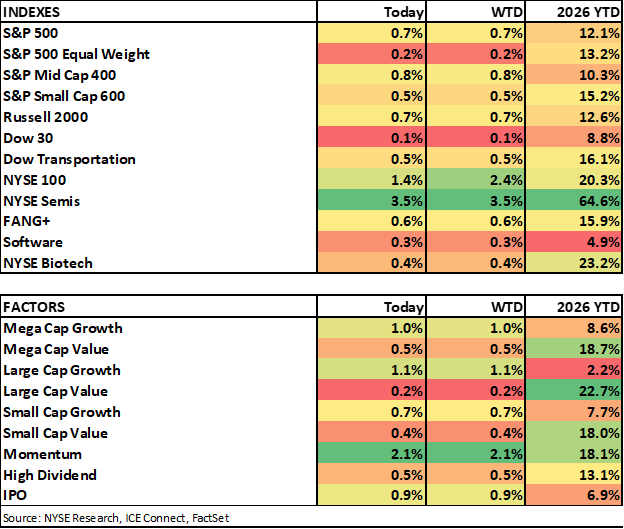
The S&P 500 is starting the week strongly as the Sports Equinox falls upon us- the 33rd time in history that the MLB, NFL, NBA, and NHL all host games on the same calendar day. The S&P is up 0.7% and near its highs. The equal-weight is trailing however as mega caps and tech lead (NYSE 100 +1.4%, NYSE Semis +3.5%). The Russell 2000 is in line. After a slow start tech moved higher, with those neoclouds and “powered shell providers” that Musk referenced rallying sharply off their lows (WULF +10%, GLXY +6%, CRWV +4%).
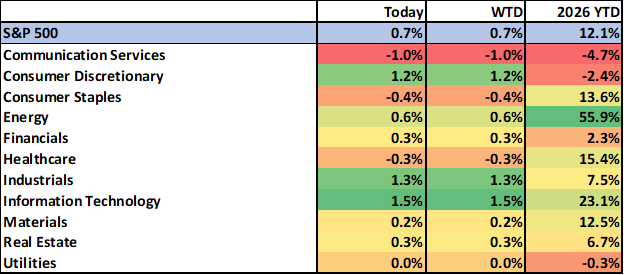
Tech, Industrials and Consumer Discretionary are leading as the AI-linked stocks are rallying. For Consumer Discretionary TSLA Is +6% and AMZN +1%. Travel & Leisure and apparel are also higher. Industrials are seeing broad strength with AI-linked stocks leading the way (GEV +5%, FIX +8%). Healthcare is lagging with Med Devices and managed care broadly lower while Merck and Moderna are lower on trial results. Comm Services is down as well with Telecom lower after VZ earnings while Media and Entertainment also are in the red.
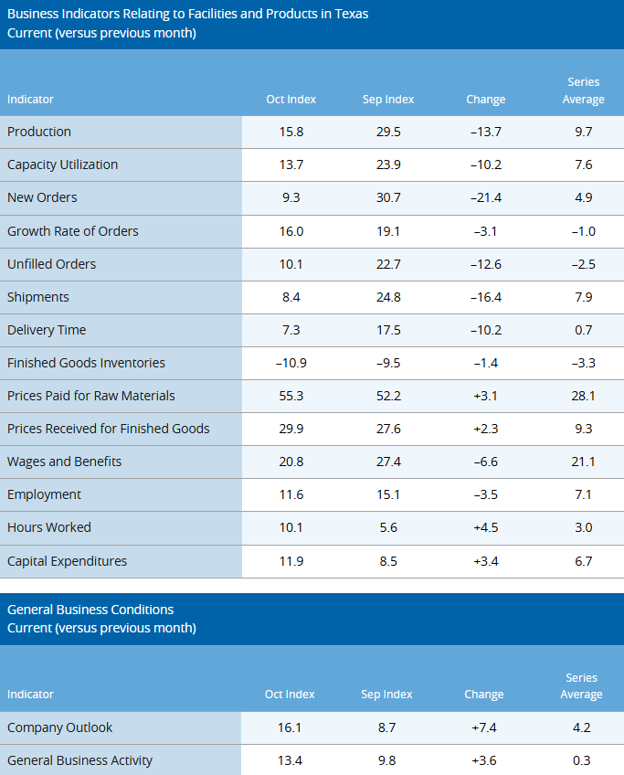
With the Fed meeting ahead of us on Wednesday, the treasury curve is twisting with short-end yields higher while the long-end moves lower. The 2y auction today tailed by 0.3bp. The Dallas Fed Manufacturing Index had some divergent results. Sentiment for General Business Conditions rose from last month but most line items fell, including Production and New Orders. Most readings remained well above their averages.
- US 2yr +3bps to 4.72%, 5yr +1bps to 4.82%, 10yr -1bps to 4.98%, 30yr -3bps to 5.30%
- USD index: +$0.07 to $101.72
The Chicago Fed National Activity Index increased to 0.07 from -0.08 last month. Production-related indicators contributed the most to the gain, while Personal Consumption and Housing lowered the reading. Overall, forty-five of the 85 individual indicators made positive contributions to the index.
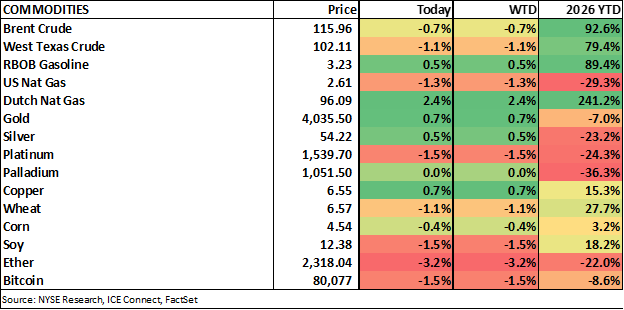
Brent crude is down ~1%. US natural gas is down as well but off its lows. Meanwhile European gas continues to reach new highs. Gold and silver are up modestly as is copper. Ag is lower following the Brazilian election and Russia-Ukraine peace talks. Crypto is getting hit with Bitcoin struggling to hold $80K.
The major story in international markets is the shellacking that Brazilian equities are seeing following election results. Major European indices closed near their highs, up ~1% with broad-based strength. Outside of Santander (-3.5% on Brazil news) banks were up 1-2% across the region. It was a mixed overnight session in Asia with tech under pressure, weighing on the Nikkei and Kospi. China’s Communist Party Plenum is underway with local indices trading modestly higher.
Tomorrow’s data will include Durable Goods, Home Prices, New Home Sales and Consumer Confidence, along with the 5y auction.
Earnings:
- After-Market: AGYS, AMKR, ARE, BRO, BRX, CDNS, CINF, CLS, DORM, FLXS, GBX, HIG, HWKN, NE, NUE, PECO, PFG, PSA, PSMT, RMBS, VLRS, WELL, WHR
- Pre-Market (Tues): ABG, AIT, AMT, ASM Int, AWI, BA, CBU, CMS, CNC, CNP, CVLT, ECL, FCX, GLW, GLXY, HCA, HLT, HRI, HUBB, IQV, ITRI, ITW, IVZ, JBLU, JCI, KO, LECO, NVS, PCAR, PII, PNR, PYPL, RCL, RGEN, SHW, SMPL, SOFI, SPGI, TNL, TRU, UPS, WSO, XYL
- After-Market (Tues): ACGL, APAM, BKR, BXP, CAKE, CHE, CR, CSGP, CZR, ENPH, EQT, ESS, EXLS, EXR, FE, FFIV, HIW, HOOD, ICLR, LOGI, LSTR, MANH, MCRI, NOV, NXPI, OI, OKE, PPG, RNR, RRC, RUSHA, SKHY, ST, STAG, STX, TER, TRMK, UCTT, UHS, V, VTR, WERN, WM, WPC
Economic Data:
US:
- Dallas Fed Manufacturing: 13.4 vs prior 9.8
- Chicago Fed Natl Index: +0.07 vs prior -0.08
Global:
- Spain PPI: 18.3% prior 13.2%
- Germany Ifo Current conditions / Expectations: 88. 8 / 91.6 vs. 89.9 / 90 cons, prior 89.5 / 90.4
STRAIGHT FROM THE TRADING FLOOR
by Michael P. Reinking, CFA - Sr. Market Strategist
Published on 10/26/26 (a/o 9:00 am)
Good morning,
Equity markets were mixed last week with tech underperforming for the third consecutive week. The S&P 500 fell 0.5% as the AI trade continued to unwind amidst growing concerns about capital constraints. Oil prices were up ~5% trading to fresh highs. However, Treasury yields pulled back. This helped the equal-weight and small/midcap indices outperform.
It was a somewhat quiet weekend on the news front though it has gotten a little busier this morning. The big headlines were the surprise victories by Lula in Brazil and the New York Football Giants in Houston. After loosing in the first round of voting incumbent Lula shockingly won in the runoff. There is some controversy around the extension of voting with Bolsonaro looking to have the results annulled. Brazilian markets rallied sharply after the first round of voting but look like they will give back all of those gains and then some (EWZ -25%).
Back stateside the focus continues to revolve around the AI trade ahead of a big week of earnings. Elon Musk threw a little fuel on the neocloud fire as SpaceX reportedly closed a $40B round of financing . After highlighting the repricing in debt markets for data center financing he said, “That means the 200+ neoclouds are going to see guppy-level death and consolidation. Some will make it through, but not many.” The neoclouds are under pressure again this morning down 2% - 5% in the pre-market. Meta announced that it was going to raise up to $95B in capital. This would be broken up into $22.5B in Class A shares, with the big three chip makers potentially buying $5B each, $12.5 in preferred stock and $60B in the new Class C shares in 2027. This highlights that the company is not planning on slowing its infrastructure spending. The stock has been wildly volatile in the pre-market trading in ~10% range, currently trading slightly lower. Meanwhile Amazon’s CEO Jassy said much of its 2027 cloud capacity has been booked. The long awaited Anthropic S1 just hit.
Futures opened modestly higher overnight, pulled back during the Asia session and but are back in the upper third of the overnight range. S&P futures and Dow futures are up ~0.3%.

The only US economic data on the calendar is the Dallas Manufacturing after the open. Treasury yields are hovering around unchanged with a slight flattening of the curve. The USD index has been grinding slightly higher throughout the morning.
It was a mixed overnight session in Asia with the tech heavy Nikkei and Kospi both under pressure given the AI concerns. China’s Communist Party Plenum is getting underway with local indices trading modestly higher. European indices are recouping some of last week’s losses trading near session highs. Financials, ex-Santander given Brazil exposure, are trading higher. Autos, manufacturing and pockets of tech are outperforming while staples and energy are lower. After the close Moody’s left France’s credit rating unchanged which has local yields down 2-10bps across the curve narrowing the spread vs. Bunds.

After last week’s move higher oil prices are pulling back modestly as there was no escalation over the weekend and as Iranian officials meet with officials from Turkey, Saudia Arabia and Pakistan. Press continues to suggest that President Trump is leaning towards a resumption of strikes. Israel’s legislative elections will be held tomorrow. US November natural futures continue to be under pressure down >4%. There was also big M&A transaction within that space with EQT announcing it will acquire RRC for ~$13B, in an all-stock transaction. The metals complex is trying to stabilize after selling off last week. Ag is under pressure after the Brazil election results as the currency weakens increasing expectations for exports. Coffee and sugar down ~3% while soy is off >1.5%. Crypto is adding to last week’s losses. Bitcoin broke below 80k over the weekend but is currently hovering right around that level.

Economic Data:
US:
Equity markets were mixed last week with tech underperforming for the third consecutive week. The S&P 500 fell 0.5% as the AI trade continued to unwind amidst growing concerns about capital constraints. Oil prices were up ~5% trading to fresh highs. However, Treasury yields pulled back. This helped the equal-weight and small/midcap indices outperform.
It was a somewhat quiet weekend on the news front though it has gotten a little busier this morning. The big headlines were the surprise victories by Lula in Brazil and the New York Football Giants in Houston. After loosing in the first round of voting incumbent Lula shockingly won in the runoff. There is some controversy around the extension of voting with Bolsonaro looking to have the results annulled. Brazilian markets rallied sharply after the first round of voting but look like they will give back all of those gains and then some (EWZ -25%).
Back stateside the focus continues to revolve around the AI trade ahead of a big week of earnings. Elon Musk threw a little fuel on the neocloud fire as SpaceX reportedly closed a $40B round of financing . After highlighting the repricing in debt markets for data center financing he said, “That means the 200+ neoclouds are going to see guppy-level death and consolidation. Some will make it through, but not many.” The neoclouds are under pressure again this morning down 2% - 5% in the pre-market. Meta announced that it was going to raise up to $95B in capital. This would be broken up into $22.5B in Class A shares, with the big three chip makers potentially buying $5B each, $12.5 in preferred stock and $60B in the new Class C shares in 2027. This highlights that the company is not planning on slowing its infrastructure spending. The stock has been wildly volatile in the pre-market trading in ~10% range, currently trading slightly lower. Meanwhile Amazon’s CEO Jassy said much of its 2027 cloud capacity has been booked. The long awaited Anthropic S1 just hit.
Futures opened modestly higher overnight, pulled back during the Asia session and but are back in the upper third of the overnight range. S&P futures and Dow futures are up ~0.3%.
The only US economic data on the calendar is the Dallas Manufacturing after the open. Treasury yields are hovering around unchanged with a slight flattening of the curve. The USD index has been grinding slightly higher throughout the morning.
- US 2yr +2bps to 4.71%, 5yr +1bps to 4.82%, 10yr -1bps to 4.99%, 30yr -2bps to 5.31%
- USD index: +$0.14 to $101.79
It was a mixed overnight session in Asia with the tech heavy Nikkei and Kospi both under pressure given the AI concerns. China’s Communist Party Plenum is getting underway with local indices trading modestly higher. European indices are recouping some of last week’s losses trading near session highs. Financials, ex-Santander given Brazil exposure, are trading higher. Autos, manufacturing and pockets of tech are outperforming while staples and energy are lower. After the close Moody’s left France’s credit rating unchanged which has local yields down 2-10bps across the curve narrowing the spread vs. Bunds.
After last week’s move higher oil prices are pulling back modestly as there was no escalation over the weekend and as Iranian officials meet with officials from Turkey, Saudia Arabia and Pakistan. Press continues to suggest that President Trump is leaning towards a resumption of strikes. Israel’s legislative elections will be held tomorrow. US November natural futures continue to be under pressure down >4%. There was also big M&A transaction within that space with EQT announcing it will acquire RRC for ~$13B, in an all-stock transaction. The metals complex is trying to stabilize after selling off last week. Ag is under pressure after the Brazil election results as the currency weakens increasing expectations for exports. Coffee and sugar down ~3% while soy is off >1.5%. Crypto is adding to last week’s losses. Bitcoin broke below 80k over the weekend but is currently hovering right around that level.
Economic Data:
US:
- 10:30 Dallas Manufacturing
- 11:30 3/6mo T-Bill auction
- 1:00 2yr Auction
- Spain PPI: 18.3% prior 13.2%
- Germany Ifo Current conditions/Expectations: 88.8/91.6 vs. 89.9/90 cons., prior 89.5/90.4


By submitting this form you hereby expressly grant permission to use the information included thereunder to contact you for the purposes of sending periodic updates about ICE and/or its affiliates. Certain indices mentioned above are administered by ICE Data Indices, LLC.
Your contact information will not be used for any purpose other than that for which your consent has been given. To learn more about our privacy policy, please click here.
© 2025 Intercontinental Exchange, Inc. All rights reserved. Intercontinental Exchange and ICE are trademarks of Intercontinental Exchange, Inc. or its affiliates. For more information regarding registered trademarks, limitations, restrictions, and other important information, please visit intercontinentalexchange.com/terms-of-use.